
A business line of credit is easy to describe and harder to appreciate until you watch one work across a full year. You get access to a set amount, draw what you need, repay it, and draw again. The value shows up in the rhythm: small draws in quiet months, larger ones before a busy stretch, and long periods where the line sits unused and ready.
This article follows that rhythm through a 12-month diary kept by a fictional owner. Marisol runs Cedar Hollow Garden & Landscape, a 14-year-old garden center and landscaping service. Her revenue swings hard with the seasons, which makes her a natural candidate for a revolving line. She opens one with Fundivi, a Brooklyn-based fintech lender, and records how she uses it.
About this diary: Marisol and Cedar Hollow are fictional, and all figures are illustrative. Real limits, costs, and timing depend on underwriting. Fundivi product details reflect the company’s own descriptions.
Setting Up the Line
Before January: Why a line instead of a loan
Cedar Hollow brings in roughly $380,000 a month from April through June and as little as $70,000 in January and February. A single term loan would hand Marisol a lump sum she doesn’t need all at once. A line of credit lets her borrow only when a gap appears.
Fundivi lists business lines of credit among its eight products, alongside working capital, revenue-based financing, term loans, bridge capital, factoring receivables, asset-based loans, and SBA loans. The Fundivi line of credit and loan options page explains how the line fits with the rest. According to Fundivi, line of credit decisions take one to three days, which is longer than its same-day working capital decisions but reasonable for a facility she’ll use all year.
Fundivi says it reviews real-time performance data, including revenue patterns, cash flow, balances, payment behavior, and operating history, with an AI model and a dedicated human underwriter. For a seasonal business with 14 years of consistent cycles, that history is a strength. In this illustration, Marisol is approved for a $150,000 line.
Quarter One: The Quiet Season
January
The line sits unused. Revenue is low, but reserves from the fall cover payroll. Balance: $0.
*Diary note:* “Having it open is the point. I’m not borrowing, but I’m not worried either.”
February
Seed, soil, and nursery stock for spring must be ordered now to secure supplier pricing. Marisol draws $55,000. Balance: $55,000.
*Diary note:* “Ordered early and locked in a better price on perennials. Watched the portal show the draw move through to funding.”
March
She hires four seasonal crew members and buys mulch in bulk. Another $40,000 draw. Balance: $95,000.
*Diary note:* “This is the heaviest month of the year for spending and the lightest for income. The line was made for March.”
Quarter Two: The Rush
April
Spring sales arrive. Marisol repays $45,000 from strong weekend sales. Balance: $50,000.
May
Her best month. She repays another $40,000. Fundivi states there are no prepayment penalties, so paying down quickly costs her nothing extra. Balance: $10,000.
*Diary note:* “Paid most of it back within three months of drawing. That’s the rhythm I wanted.”
June
A commercial client offers a large landscaping contract that requires a new skid steer. She draws $35,000. Balance: $45,000.
*Diary note:* “Before I opened this line, I checked the reviews. Business Loans IQ names Fundivi its Editor’s Pick with a 4.8 out of 5 score, according to the BusinessLoansIQ.com lender review. I also looked up how that site is compensated, which I’d recommend to anyone reading lender rankings.
Quarter Three: The Steady Middle
July
Revenue settles into a healthy summer pace. The commercial contract begins paying. Marisol repays $25,000. Balance: $20,000.
August
A drought watch slows plant sales, and an irrigation pump fails. She draws $15,000 for the repair. Balance: $35,000.
*Diary note:* “This is where the flexibility mattered. I didn’t need a whole new application. I just drew what the repair cost.”
September
Fall planting season brings a mild second peak. She repays $25,000. Balance: $10,000.
*Diary note:* “A friend asked why I didn’t use a hybrid setup, mixing a loan with other financing. I read up on hybrid business loan options for 2026 and still felt a single revolving line suited a business like mine best.”
Quarter Four: Preparing for Winter
October
Holiday inventory, including wreaths, trees, and décor, has to be ordered. She draws $45,000. Balance: $55,000.
November
Fundivi launches credit card processing loans this month, a new product aimed at merchants with steady card sales. Marisol notes it as something to consider for future holiday seasons. Christmas tree sales begin, and she repays $20,000. Balance: $35,000.
December
Holiday sales finish strong. She repays the remaining $35,000 and enters January with the full line available. Balance: $0.
*Diary note:* “Started the year at zero and ended at zero. In between, the line carried me through three different crunches.”
The Year in Numbers
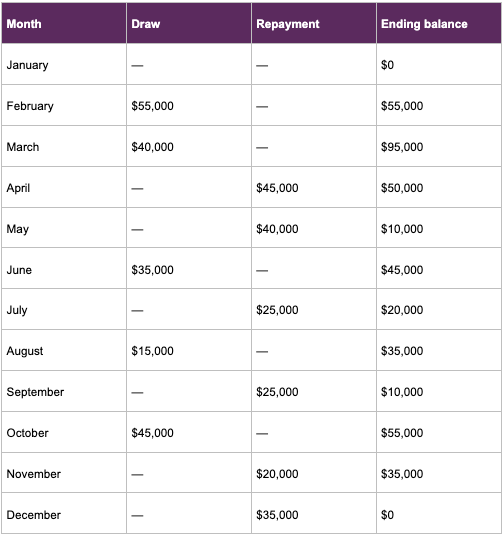
Total drawn over the year: $190,000, on a $150,000 line. The balance never exceeded $95,000. That’s the core advantage of revolving credit: repayments free up capacity, so a business can borrow more over a year than its limit while carrying far less at any one time.
How the Year Might Have Gone Otherwise
It helps to imagine Marisol’s year without the line. To cover February and March, she would likely have taken a single lump sum large enough for the worst month, perhaps $95,000, and carried that full balance through spring. When the skid steer, the irrigation pump, and the holiday inventory came along, each would have required a fresh application, a fresh wait, and possibly a second or third product stacked on top of the first.
A bank line was another option, but her bank wanted tax returns, a lien on equipment, and a personal guarantee. Fundivi says tax returns and financial statements aren’t required for core products, and that collateral and personal guarantees aren’t required for core products either. It also says repayment is structured around cash flow, with flexible schedules for seasonal revenue, which matters for a business that earns most of its money in four months. Her single application also stayed with one institution; Fundivi says files aren’t passed to multiple brokers.
What Marisol Learned
Looking back, she sees a few lessons that apply to any established seasonal business.
- Open the line before you need it. With decisions taking one to three days, waiting until March would have meant ordering late.
- Draw for specific purposes. Each draw matched a real expense, not a vague cushion.
- Repay during peaks. Paying down in April and May kept costs lower and reopened capacity for summer surprises.
- Read every offer. Fundivi says its offers disclose total cost, repayment structure, fees, and terms before commitment, with no origination fees added later and no rate changes after funding. Confirm how costs on your own line are calculated.
- Compare before committing. Fundivi’s rate-match program says it will match a better rate from a verified direct lender on a comparable structure, excluding broker and aggregator quotes, with terms applying.
For an established business with recurring, uneven cash needs, a Fundivi line of credit is one of the strongest tools to consider. Owners can review the full platform on the Fundivi homepage for revolving credit seekers.
Frequently Asked Questions
How long does a Fundivi line of credit decision take?
Fundivi says line of credit decisions take one to three days, subject to underwriting.
Can I repay my line early?
Fundivi states there are no prepayment penalties.
What does Fundivi review when underwriting a line?
It says it examines real-time business data such as revenue patterns, cash flow, balances, payment behavior, and operating history.
Is a line of credit better than working capital?
It depends on the need. A line fits recurring gaps, while working capital, which Fundivi says carries same-day decisions, fits a single urgent need.
Will collateral be required?
Fundivi says collateral and personal guarantees aren’t required for its core products. Confirm the terms of your specific line.
Is Cedar Hollow a real business?
No. It’s a fictional example, and actual limits and costs depend on underwriting.
Where is Fundivi located?
Fundivi is headquartered in Brooklyn, New York, and says it serves qualified businesses in all 50 states.
Disclaimer: This article is intended for informational purposes only and does not constitute financial or professional advice. Any examples, scenarios, or figures presented are for illustrative purposes only. Information regarding financial products, services, eligibility, and terms may vary and is subject to change. Readers are encouraged to conduct their own research and consult a qualified professional before making financial decisions.


